
Circle (CRCL)
Issuer of USDC and EURC with payment, interoperability, and developer infrastructure.
Something off on this page? Send us feedback.
Circle runs a digital-dollar business whose reserve interest pays nearly every bill. Around that cash engine, it is building payment routes, developer tools and its own transaction network so more money stays inside Circle’s system. The diversification is real but early: the company still hangs on USDC balances, interest rates and costly distribution partners.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
6 in detail · 14 more below
USDC and EURC
These cash-backed digital dollars and euros produced $2.637 billion of reserve income in FY2025. More coins help, but falling interest rates can blunt the gain.
Competes with USDt (Tether) · PayPal USD (Paxos/PayPal) · EUR CoinVertible (SG-FORGE)
In plain English
Think of USDC and EURC as digital cash-register chips: each one is issued only after someone supplies an equal dollar or euro, and holders can swap it back. USDC is the giant; EURC uses the same idea at a much smaller scale.
Circle keeps the backing in cash and short-term investments and earns interest while the coins remain in circulation. Exchanges and payment firms make the coins easy to use, but Circle pays heavily for that reach. The result depends on three moving parts: how many coins people hold, what the reserves earn, and how much distributors take.
USYC
A digital share of a short-term government-debt fund, USYC gives eligible non-U.S. institutions the investment yield. Circle keeps 10% of that yield; the test is whether more trading venues accept it to cover possible losses.
Competes with BUIDL (BlackRock/Securitize) · iBENJI/BENJI (Franklin Templeton)
In plain English
USYC is closer to a savings product than to digital cash. It represents a share of a fund holding short-term U.S. government debt and related lending agreements, so eligible institutions outside the United States can earn the underlying investment return while moving the holding through digital systems.
Circle makes money by keeping a slice of the yield and charging small fees on large subscriptions and withdrawals. The product becomes more useful when trading venues accept it as property posted to cover possible losses. Its current size is too uncertain to use as a dependable anchor.
Circle Payments Network
A network for banks and payment firms to send money across borders using Circle’s digital cash. At its June 2026 pace, payments would total $14.7 billion over a year, but meaningful fees remain a later goal.
Competes with Ripple Payments (Ripple) · Network for Payments (Fireblocks)
In plain English
Sending business money to another country often means passing it through several banks, currencies and local payment companies. Circle Payments Network links approved banks and payment firms so the middle of that trip can happen with USDC instead.
A sender hands over ordinary money, USDC carries the value between participating firms, and a local partner pays ordinary money out at the other end. Circle provides the accounts, connections and rule-checking needed to make that handoff work. More institutions and payment traffic make the network more useful, but the company has not yet turned that activity into meaningful revenue.
Circle Mint and xReserve
Mint is the institutional doorway for issuing and redeeming Circle’s digital cash; xReserve sells other digital networks a subscription for compatible, USDC-backed coins. Most core Mint movements are free, so adoption matters more than fees.
Competes with Stablecoin Issuance (Paxos) · Universal Stablecoin Platform (M0)
In plain English
This is the service counter behind Circle’s coins. Approved exchanges, financial-technology firms and other institutions use Circle Mint to turn bank money into USDC or EURC, hold it, and turn it back again. Ordinary issuance and two-business-day withdrawals are free; faster withdrawals can carry a small charge.
xReserve serves digital networks where USDC itself is not available. A network pays for permission and software to issue its own compatible coin, while keeping it backed by and redeemable for USDC. Circle earns a subscription and extends its cash system without placing the original coin everywhere.
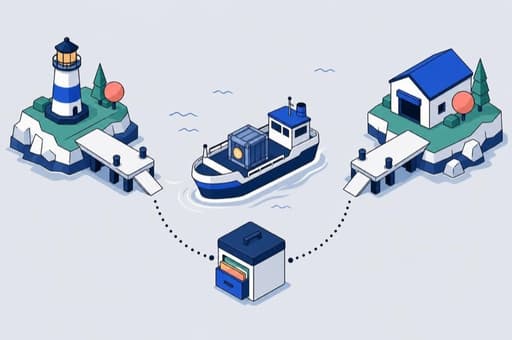
Cross-Chain Transfer Protocol and Gateway
CCTP moves USDC between otherwise separate digital networks, while Gateway presents one balance across them. CCTP had carried more than $126 billion by December 2025; standard trips are generally free, leaving paid speed as the direct business.
Competes with Native Token Transfers (Wormhole) · Omnichain Fungible Token (LayerZero)
In plain English
Digital networks can behave like islands: money on one does not automatically exist on another. CCTP solves that by destroying a USDC coin on the departure side and issuing an equal one at the destination. Gateway lets a customer see and use one balance across several islands.
Wallets, exchanges and routing services use these tools to move customer money or refill supplies where needed. Circle usually charges nothing for the standard route and collects a small fee when users choose the faster route. Even free trips can help by making USDC easier to hold and use more widely.
Arc and ARC Token
Arc is Circle’s business transaction network, currently open only to selected users and due to open publicly in September 2026. The real test is whether heavy trial activity becomes paid use.
Competes with Tempo (Stripe/Paradigm) · Canton Network (Digital Asset)
In plain English
Instead of placing tools on someone else’s rails, Circle is building the rails. Arc is a new digital transaction network designed for business payments, with fees paid in dollars and controls that can keep transaction details private. A planned ARC coin would help operate and govern the network.
Arc can pull Circle’s digital cash, transfer tools and payment network into one place. Businesses would pay to move value there, while operators help verify the shared record. For now it remains a bet: the network is private, the future coins have not been delivered, and busy testing does not prove customers will pay.


 USDC and EURCThese cash-backed digital dollars and euros produced $2.637 billion of reserve income in FY2025. More coins help, but falling interest rates can blunt the gain.
These cash-backed digital dollars and euros produced $2.637 billion of reserve income in FY2025. More coins help, but falling interest rates can blunt the gain.
In plain English
Think of USDC and EURC as digital cash-register chips: each one is issued only after someone supplies an equal dollar or euro, and holders can swap it back. USDC is the giant; EURC uses the same idea at a much smaller scale.
Circle keeps the backing in cash and short-term investments and earns interest while the coins remain in circulation. Exchanges and payment firms make the coins easy to use, but Circle pays heavily for that reach. The result depends on three moving parts: how many coins people hold, what the reserves earn, and how much distributors take.
Competes with USDt (Tether) · PayPal USD (Paxos/PayPal) · EUR CoinVertible (SG-FORGE)
 USYCA digital share of a short-term government-debt fund, USYC gives eligible non-U.S. institutions the investment yield. Circle keeps 10% of that yield; the test is whether more trading venues accept it to cover possible losses.
A digital share of a short-term government-debt fund, USYC gives eligible non-U.S. institutions the investment yield. Circle keeps 10% of that yield; the test is whether more trading venues accept it to cover possible losses.
In plain English
USYC is closer to a savings product than to digital cash. It represents a share of a fund holding short-term U.S. government debt and related lending agreements, so eligible institutions outside the United States can earn the underlying investment return while moving the holding through digital systems.
Circle makes money by keeping a slice of the yield and charging small fees on large subscriptions and withdrawals. The product becomes more useful when trading venues accept it as property posted to cover possible losses. Its current size is too uncertain to use as a dependable anchor.
Competes with BUIDL (BlackRock/Securitize) · iBENJI/BENJI (Franklin Templeton)
 Circle Payments NetworkA network for banks and payment firms to send money across borders using Circle’s digital cash. At its June 2026 pace, payments would total $14.7 billion over a year, but meaningful fees remain a later goal.
A network for banks and payment firms to send money across borders using Circle’s digital cash. At its June 2026 pace, payments would total $14.7 billion over a year, but meaningful fees remain a later goal.
In plain English
Sending business money to another country often means passing it through several banks, currencies and local payment companies. Circle Payments Network links approved banks and payment firms so the middle of that trip can happen with USDC instead.
A sender hands over ordinary money, USDC carries the value between participating firms, and a local partner pays ordinary money out at the other end. Circle provides the accounts, connections and rule-checking needed to make that handoff work. More institutions and payment traffic make the network more useful, but the company has not yet turned that activity into meaningful revenue.
Competes with Ripple Payments (Ripple) · Network for Payments (Fireblocks)
 Circle Mint and xReserveMint is the institutional doorway for issuing and redeeming Circle’s digital cash; xReserve sells other digital networks a subscription for compatible, USDC-backed coins. Most core Mint movements are free, so adoption matters more than fees.
Mint is the institutional doorway for issuing and redeeming Circle’s digital cash; xReserve sells other digital networks a subscription for compatible, USDC-backed coins. Most core Mint movements are free, so adoption matters more than fees.
In plain English
This is the service counter behind Circle’s coins. Approved exchanges, financial-technology firms and other institutions use Circle Mint to turn bank money into USDC or EURC, hold it, and turn it back again. Ordinary issuance and two-business-day withdrawals are free; faster withdrawals can carry a small charge.
xReserve serves digital networks where USDC itself is not available. A network pays for permission and software to issue its own compatible coin, while keeping it backed by and redeemable for USDC. Circle earns a subscription and extends its cash system without placing the original coin everywhere.
Competes with Stablecoin Issuance (Paxos) · Universal Stablecoin Platform (M0)
 Cross-Chain Transfer Protocol and GatewayCCTP moves USDC between otherwise separate digital networks, while Gateway presents one balance across them. CCTP had carried more than $126 billion by December 2025; standard trips are generally free, leaving paid speed as the direct business.
CCTP moves USDC between otherwise separate digital networks, while Gateway presents one balance across them. CCTP had carried more than $126 billion by December 2025; standard trips are generally free, leaving paid speed as the direct business.
In plain English
Digital networks can behave like islands: money on one does not automatically exist on another. CCTP solves that by destroying a USDC coin on the departure side and issuing an equal one at the destination. Gateway lets a customer see and use one balance across several islands.
Wallets, exchanges and routing services use these tools to move customer money or refill supplies where needed. Circle usually charges nothing for the standard route and collects a small fee when users choose the faster route. Even free trips can help by making USDC easier to hold and use more widely.
Competes with Native Token Transfers (Wormhole) · Omnichain Fungible Token (LayerZero)
 Arc and ARC TokenArc is Circle’s business transaction network, currently open only to selected users and due to open publicly in September 2026. The real test is whether heavy trial activity becomes paid use.
Arc is Circle’s business transaction network, currently open only to selected users and due to open publicly in September 2026. The real test is whether heavy trial activity becomes paid use.
In plain English
Instead of placing tools on someone else’s rails, Circle is building the rails. Arc is a new digital transaction network designed for business payments, with fees paid in dollars and controls that can keep transaction details private. A planned ARC coin would help operate and govern the network.
Arc can pull Circle’s digital cash, transfer tools and payment network into one place. Businesses would pay to move value there, while operators help verify the shared record. For now it remains a bet: the network is private, the future coins have not been delivered, and busy testing does not prove customers will pay.
Competes with Tempo (Stripe/Paradigm) · Canton Network (Digital Asset)
Named in filings, launches and programs
- StableFXPlatformA trial-stage service for institutions to exchange currencies through digital networks; announced in November 2025 and still listed as current.
- Circle WalletsPlatformSoftware that lets businesses place Circle-managed or user-controlled digital wallets inside their own apps.
- Circle ContractsServiceReady-made software patterns for creating digital assets and automating how they move.
- PaymasterEcosystemLets an app cover network charges for users, or lets users pay those charges in USDC.
- Agent StackPlatform · RampingTools launched in May 2026 for automated software agents to find paid services and send payments; more than nine hundred services were listed.
- cirBTCProductA bitcoin-backed digital asset for institutions to post against trades and move across digital networks.
- Circle National TrustBrandA federally supervised trust company opened in July 2026 to safeguard assets for Circle affiliates; it does not take bank deposits.
- Circle New York TrustBrandA New York-chartered trust company added in July 2026 as another regulated safeguarding arm.
- Circle Alliance ProgramEcosystemA partner community that had more than one thousand members at the end of 2025.
- Coinbase Collaboration AgreementCustomer programA renewable distribution and income-sharing deal that makes Coinbase Circle’s largest disclosed cost partner.
- Binance distribution agreementsCustomer programTreasury, marketing and wallet-promotion arrangements that reward Binance for helping USDC balances and activity grow.
- BlackRock reserve-management programCustomer programBlackRock manages the main reserve fund and is promised most eligible U.S.-managed reserves under a four-year agreement.
- Intuit × Circle partnershipCustomer program · AnnouncedA multi-year plan to bring USDC infrastructure to Intuit products; neither revenue nor committed spending was disclosed.
- Polymarket USDC settlement partnershipCustomer program · AnnouncedA planned shift to the version of USDC that Circle issues directly for trading deposits and final payments; its economics were not disclosed.
StableFXPlatform
A trial-stage service for institutions to exchange currencies through digital networks; announced in November 2025 and still listed as current.
Circle WalletsPlatform
Software that lets businesses place Circle-managed or user-controlled digital wallets inside their own apps.
Circle ContractsService
Ready-made software patterns for creating digital assets and automating how they move.
PaymasterEcosystem
Lets an app cover network charges for users, or lets users pay those charges in USDC.
Agent StackPlatform · Ramping
Tools launched in May 2026 for automated software agents to find paid services and send payments; more than nine hundred services were listed.
cirBTCProduct
A bitcoin-backed digital asset for institutions to post against trades and move across digital networks.
Circle National TrustBrand
A federally supervised trust company opened in July 2026 to safeguard assets for Circle affiliates; it does not take bank deposits.
Circle New York TrustBrand
A New York-chartered trust company added in July 2026 as another regulated safeguarding arm.
Circle Alliance ProgramEcosystem
A partner community that had more than one thousand members at the end of 2025.
Coinbase Collaboration AgreementCustomer program
A renewable distribution and income-sharing deal that makes Coinbase Circle’s largest disclosed cost partner.
Binance distribution agreementsCustomer program
Treasury, marketing and wallet-promotion arrangements that reward Binance for helping USDC balances and activity grow.
BlackRock reserve-management programCustomer program
BlackRock manages the main reserve fund and is promised most eligible U.S.-managed reserves under a four-year agreement.
Intuit × Circle partnershipCustomer program · Announced
A multi-year plan to bring USDC infrastructure to Intuit products; neither revenue nor committed spending was disclosed.
Polymarket USDC settlement partnershipCustomer program · Announced
A planned shift to the version of USDC that Circle issues directly for trading deposits and final payments; its economics were not disclosed.