
Altria Group (MO)
Sells Marlboro cigarettes, oral tobacco, nicotine pouches and NJOY e-vapor products.
Something off on this page? Send us feedback.
Altria is overwhelmingly a U.S. cigarette company, with Marlboro still paying nearly all the bills. It is trying to move nicotine users toward pouches and eventually heated tobacco, but that shift is uneven: pouches are gaining attention, while its main vapor product is off shelves and cigarettes remain the cash engine.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
7 in detail · 8 more below
Marlboro
Altria's premium cigarette family is the company’s center of gravity. It supplied an estimated three-quarters of FY2025 revenue, but U.S. cigarette demand keeps shrinking, so price increases must keep outrunning lost packs.
Competes with Newport (Reynolds American / BAT) · Camel (Reynolds American / BAT)
In plain English
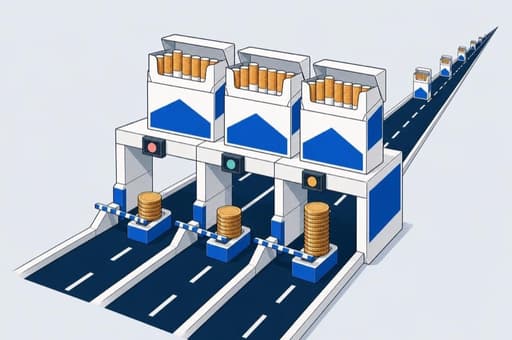
Think of Marlboro as a very large tollbooth on a road carrying fewer cars each year. Adult smokers buy packs repeatedly, stores restock through wholesalers, and Altria charges more per pack to offset declining traffic.
Almost all sales are in the United States, moving through Altria’s distributor to more than three hundred thousand retailers. Two unnamed wholesalers carried forty-two percent of FY2025 revenue; older filings point to national wholesalers Core-Mark and McLane as the likely pair. The brand’s reach gives price increases unusual force, but fewer cigarettes are sold every year and more smokers are moving toward cheaper brands.
Basic
A cheaper cigarette meant to keep budget-conscious smokers inside Altria. Its store reach and share are rising quickly within a shrinking market, but every switch from Marlboro brings in less money per cigarette.
Competes with Pall Mall (Reynolds American / BAT) · Maverick and Crowns (ITG Brands / Imperial Brands)
In plain English
When household budgets tighten, some smokers trade down instead of quitting. Basic is Altria’s lower-priced answer: the same broad factory and delivery system puts a cheaper pack into selected stores where demand for value brands is strongest.
The retailer sells the pack, a wholesaler replenishes it, and Altria earns on each shipment. Support had reached roughly thirty-five thousand stores by midyear. That growth helps defend cigarette volume, yet it is a defensive win—Basic can take customers from rival discount brands or from Marlboro, and the latter trade brings less revenue per cigarette.
Copenhagen and Skoal
Traditional moist tobacco sold by the can remains the bulk of Altria’s oral business. Copenhagen and Skoal volumes fell by double digits in early 2026 as nicotine pouches took more shelf space.
Competes with Grizzly (American Snuff / Reynolds American / BAT) · Kodiak (American Snuff / Reynolds American / BAT)
In plain English
The unglamorous second cash engine. Copenhagen and Skoal are cans of cut, moist tobacco that users place between gum and lip. People buy another can when the last one runs out, giving Altria the same repeat-purchase rhythm as cigarettes.
Special tobacco leaves go into the cans, Altria’s U.S. Smokeless Tobacco unit makes them, and the common distribution network carries them to stores. Higher prices can cushion falling can sales, but cannot erase the direction of travel: newer leaf-free pouches now make up most oral-nicotine units, pulling shoppers away from these older brands.
on! and on! PLUS
Small leaf-free nicotine pouches are Altria’s clearest running growth product. PLUS reached national retail in March 2026, but overall on! pouch share was down from a year earlier as ZYN, VELO and Zone fought for the same shelves.
Competes with ZYN (Swedish Match / Philip Morris International) · VELO (Reynolds American / BAT) · Zone (ITG Brands / Imperial Brands)
In plain English
A pouch is a small packet tucked under the lip, delivering nicotine without smoke or loose tobacco leaf. on! is the established version; PLUS is softer and adds a compartment in the can for used pouches.
Customers keep buying replacement cans, so the business depends on habit, shelf visibility and enough legally permitted flavors and strengths. Altria makes the pouches and uses its existing store network to place them widely. PLUS reached roughly one hundred twenty thousand stores within months, but fast distribution is only the opening move: rival ZYN remains the closest target, and on!’s overall share recently slipped.
Black & Mild
Machine-made large cigars are a modest but resilient niche. Black & Mild volume grew in FY2025 and again in mid-2026 even as Altria estimated the wider large-cigar market was shrinking.
Competes with Swisher Sweets (Swisher) · Backwoods (ITG Brands / Imperial Brands)
In plain English
Here the product is a tipped, machine-made cigar rather than a cigarette. John Middleton makes it, Altria’s distributor carries it to convenience and tobacco shops, and adult buyers pay one cigar at a time or by the pack.
That familiar route to stores keeps the business simple and inexpensive to support. The unusual part is recent performance: Black & Mild shipments rose while Altria said the broader large-cigar market fell. Its durability still depends on legal flavor choices, cigar taxes and a steady supply of leaf, so a small winning niche can change quickly when the rules change.
NJOY
NJOY’s main ACE vapor system has been off U.S. shelves since March 2025. Only Daily remains, while replacement devices await permission to sell; the question is whether this costly purchase can regain meaningful scale.
Competes with Vuse Alto (R.J. Reynolds Vapor / BAT) · JUUL2 (JUUL Labs)
In plain English
NJOY sells battery devices that heat nicotine liquid into a mist, plus the replaceable liquid pods used inside them. That refill pattern should work like a coffee machine and its capsules: place the device once, then earn from repeated pod purchases.
But the machine is largely stalled. Patent-related orders stopped imports and sales of ACE, the main device, at the end of March 2025. The smaller Daily product can still be sold, and Altria is developing replacements, yet those products need federal permission before reaching stores. Until that happens, NJOY contributes almost no sales despite its expensive acquisition.
Ploom and Marlboro heated tobacco sticks
A future device-and-refill system that warms tobacco sticks rather than burning them. Altria and JTI filed for U.S. permission in August 2025, but there was still no product to sell by June 2026.
Competes with IQOS (Philip Morris International) · glo Hilo (BAT)
In plain English
Ploom has not reached U.S. shoppers yet. JTI would supply the heater; Altria would make Marlboro tobacco sticks designed to warm inside it instead of burning.
The heater starts the relationship, then every pack of sticks creates another sale—much like selling a printer and earning repeatedly from its cartridges. Altria owns three-quarters of the joint venture that would market the system in the United States. For now nobody pays because there is no U.S. product: federal reviewers must permit both the device and sticks before Altria can put them on shelves.


 MarlboroAltria's premium cigarette family is the company’s center of gravity. It supplied an estimated three-quarters of FY2025 revenue, but U.S. cigarette demand keeps shrinking, so price increases must keep outrunning lost packs.
Altria's premium cigarette family is the company’s center of gravity. It supplied an estimated three-quarters of FY2025 revenue, but U.S. cigarette demand keeps shrinking, so price increases must keep outrunning lost packs.
In plain English
Think of Marlboro as a very large tollbooth on a road carrying fewer cars each year. Adult smokers buy packs repeatedly, stores restock through wholesalers, and Altria charges more per pack to offset declining traffic.
Almost all sales are in the United States, moving through Altria’s distributor to more than three hundred thousand retailers. Two unnamed wholesalers carried forty-two percent of FY2025 revenue; older filings point to national wholesalers Core-Mark and McLane as the likely pair. The brand’s reach gives price increases unusual force, but fewer cigarettes are sold every year and more smokers are moving toward cheaper brands.
Competes with Newport (Reynolds American / BAT) · Camel (Reynolds American / BAT)
 BasicA cheaper cigarette meant to keep budget-conscious smokers inside Altria. Its store reach and share are rising quickly within a shrinking market, but every switch from Marlboro brings in less money per cigarette.
A cheaper cigarette meant to keep budget-conscious smokers inside Altria. Its store reach and share are rising quickly within a shrinking market, but every switch from Marlboro brings in less money per cigarette.
In plain English
When household budgets tighten, some smokers trade down instead of quitting. Basic is Altria’s lower-priced answer: the same broad factory and delivery system puts a cheaper pack into selected stores where demand for value brands is strongest.
The retailer sells the pack, a wholesaler replenishes it, and Altria earns on each shipment. Support had reached roughly thirty-five thousand stores by midyear. That growth helps defend cigarette volume, yet it is a defensive win—Basic can take customers from rival discount brands or from Marlboro, and the latter trade brings less revenue per cigarette.
Competes with Pall Mall (Reynolds American / BAT) · Maverick and Crowns (ITG Brands / Imperial Brands)
 Copenhagen and SkoalTraditional moist tobacco sold by the can remains the bulk of Altria’s oral business. Copenhagen and Skoal volumes fell by double digits in early 2026 as nicotine pouches took more shelf space.
Traditional moist tobacco sold by the can remains the bulk of Altria’s oral business. Copenhagen and Skoal volumes fell by double digits in early 2026 as nicotine pouches took more shelf space.
In plain English
The unglamorous second cash engine. Copenhagen and Skoal are cans of cut, moist tobacco that users place between gum and lip. People buy another can when the last one runs out, giving Altria the same repeat-purchase rhythm as cigarettes.
Special tobacco leaves go into the cans, Altria’s U.S. Smokeless Tobacco unit makes them, and the common distribution network carries them to stores. Higher prices can cushion falling can sales, but cannot erase the direction of travel: newer leaf-free pouches now make up most oral-nicotine units, pulling shoppers away from these older brands.
Competes with Grizzly (American Snuff / Reynolds American / BAT) · Kodiak (American Snuff / Reynolds American / BAT)
 on! and on! PLUSSmall leaf-free nicotine pouches are Altria’s clearest running growth product. PLUS reached national retail in March 2026, but overall on! pouch share was down from a year earlier as ZYN, VELO and Zone fought for the same shelves.
Small leaf-free nicotine pouches are Altria’s clearest running growth product. PLUS reached national retail in March 2026, but overall on! pouch share was down from a year earlier as ZYN, VELO and Zone fought for the same shelves.
In plain English
A pouch is a small packet tucked under the lip, delivering nicotine without smoke or loose tobacco leaf. on! is the established version; PLUS is softer and adds a compartment in the can for used pouches.
Customers keep buying replacement cans, so the business depends on habit, shelf visibility and enough legally permitted flavors and strengths. Altria makes the pouches and uses its existing store network to place them widely. PLUS reached roughly one hundred twenty thousand stores within months, but fast distribution is only the opening move: rival ZYN remains the closest target, and on!’s overall share recently slipped.
Competes with ZYN (Swedish Match / Philip Morris International) · VELO (Reynolds American / BAT) · Zone (ITG Brands / Imperial Brands)
 Black & MildMachine-made large cigars are a modest but resilient niche. Black & Mild volume grew in FY2025 and again in mid-2026 even as Altria estimated the wider large-cigar market was shrinking.
Machine-made large cigars are a modest but resilient niche. Black & Mild volume grew in FY2025 and again in mid-2026 even as Altria estimated the wider large-cigar market was shrinking.
In plain English
Here the product is a tipped, machine-made cigar rather than a cigarette. John Middleton makes it, Altria’s distributor carries it to convenience and tobacco shops, and adult buyers pay one cigar at a time or by the pack.
That familiar route to stores keeps the business simple and inexpensive to support. The unusual part is recent performance: Black & Mild shipments rose while Altria said the broader large-cigar market fell. Its durability still depends on legal flavor choices, cigar taxes and a steady supply of leaf, so a small winning niche can change quickly when the rules change.
Competes with Swisher Sweets (Swisher) · Backwoods (ITG Brands / Imperial Brands)
 NJOYNJOY’s main ACE vapor system has been off U.S. shelves since March 2025. Only Daily remains, while replacement devices await permission to sell; the question is whether this costly purchase can regain meaningful scale.
NJOY’s main ACE vapor system has been off U.S. shelves since March 2025. Only Daily remains, while replacement devices await permission to sell; the question is whether this costly purchase can regain meaningful scale.
In plain English
NJOY sells battery devices that heat nicotine liquid into a mist, plus the replaceable liquid pods used inside them. That refill pattern should work like a coffee machine and its capsules: place the device once, then earn from repeated pod purchases.
But the machine is largely stalled. Patent-related orders stopped imports and sales of ACE, the main device, at the end of March 2025. The smaller Daily product can still be sold, and Altria is developing replacements, yet those products need federal permission before reaching stores. Until that happens, NJOY contributes almost no sales despite its expensive acquisition.
Competes with Vuse Alto (R.J. Reynolds Vapor / BAT) · JUUL2 (JUUL Labs)
 Ploom and Marlboro heated tobacco sticksA future device-and-refill system that warms tobacco sticks rather than burning them. Altria and JTI filed for U.S. permission in August 2025, but there was still no product to sell by June 2026.
A future device-and-refill system that warms tobacco sticks rather than burning them. Altria and JTI filed for U.S. permission in August 2025, but there was still no product to sell by June 2026.
In plain English
Ploom has not reached U.S. shoppers yet. JTI would supply the heater; Altria would make Marlboro tobacco sticks designed to warm inside it instead of burning.
The heater starts the relationship, then every pack of sticks creates another sale—much like selling a printer and earning repeatedly from its cartridges. Altria owns three-quarters of the joint venture that would market the system in the United States. For now nobody pays because there is no U.S. product: federal reviewers must permit both the device and sticks before Altria can put them on shelves.
Competes with IQOS (Philip Morris International) · glo Hilo (BAT)
Named in filings, launches and programs
- Other PM USA premium cigarettesProduct lineL&M, Parliament and Virginia Slims form the non-Marlboro premium tail, together estimated at roughly three to four percent of FY2025 revenue.
- Red Seal and HuskyProduct lineLower-priced moist tobacco brands worth roughly one percent of revenue, sitting behind Copenhagen and Skoal in Altria’s traditional oral lineup.
- Export contract manufacturingCustomer program · RampingPM USA made 1.346 billion cigarettes for unnamed export customers in the first half of 2026; customer revenue is not separately disclosed.
- PMI contract manufacturing arrangementCustomer program · AnnouncedPM USA plans to make cigarettes for PMI businesses outside America, with first shipments expected in early 2027 and little FY2026 effect.
- Anheuser-Busch InBev investmentEcosystemAn 8.1% ownership stake whose beer earnings and dividends add investment income rather than nicotine sales.
- Cronos Group investmentEcosystemA 42.2% interest in a Canadian cannabinoid company, valued on Altria’s books at $319 million in June 2026.
- LOOP / Another Snus Factory interestEcosystem · AnnouncedA planned ownership interest in the maker of LOOP nicotine pouches; completion and economics were not available.
- Korea Ginseng Corporation explorationEcosystem · AnnouncedA non-binding collaboration to explore U.S. energy and wellness products using KGC products and Altria’s distribution reach.
Other PM USA premium cigarettesProduct line
L&M, Parliament and Virginia Slims form the non-Marlboro premium tail, together estimated at roughly three to four percent of FY2025 revenue.
Red Seal and HuskyProduct line
Lower-priced moist tobacco brands worth roughly one percent of revenue, sitting behind Copenhagen and Skoal in Altria’s traditional oral lineup.
Export contract manufacturingCustomer program · Ramping
PM USA made 1.346 billion cigarettes for unnamed export customers in the first half of 2026; customer revenue is not separately disclosed.
PMI contract manufacturing arrangementCustomer program · Announced
PM USA plans to make cigarettes for PMI businesses outside America, with first shipments expected in early 2027 and little FY2026 effect.
Anheuser-Busch InBev investmentEcosystem
An 8.1% ownership stake whose beer earnings and dividends add investment income rather than nicotine sales.
Cronos Group investmentEcosystem
A 42.2% interest in a Canadian cannabinoid company, valued on Altria’s books at $319 million in June 2026.
LOOP / Another Snus Factory interestEcosystem · Announced
A planned ownership interest in the maker of LOOP nicotine pouches; completion and economics were not available.
Korea Ginseng Corporation explorationEcosystem · Announced
A non-binding collaboration to explore U.S. energy and wellness products using KGC products and Altria’s distribution reach.