
Visa (V)
Processes payments and provides money movement, fraud, acceptance and issuer services.
Something off on this page? Send us feedback.
Visa runs the behind-the-scenes network that lets banks and sellers complete card payments; it does not lend shoppers the money. That familiar card business still supplies most of the revenue, while faster-growing software, fraud protection and new ways to move money are broadening what Visa sells.
Item facts: FY2025 · year ended Sep 30, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
6 in detail · 19 more below
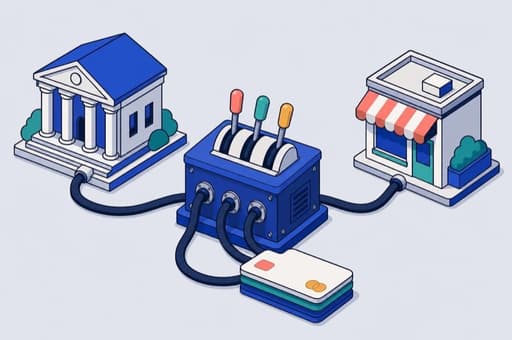
Consumer Payments
Credit, debit and prepaid card payments remain Visa's cash engine. One unnamed client supplied 11% of total FY2025 revenue; watch the rebates used to retain banks, regulation and spending that crosses borders.
Competes with Mastercard payment network (Mastercard) · American Express Global Network (American Express)
In plain English
Think of Visa as the switchboard behind a card purchase. Your bank approves the payment, the seller's bank receives it, and Visa's network passes the messages needed to check, record and finish the transaction. Visa itself is not the bank and usually does not take the risk that a shopper fails to repay.
Banks pay Visa fees tied to how much people spend, how many payments the network handles and whether money crosses borders or changes currency. More cards and more sellers make the network useful to both sides, so banks keep distributing Visa ways to pay.
Visa Intelligent Commerce
Payment controls let automated shopping assistants buy with a user's permission. By December 2025, only hundreds of controlled purchases had been completed; watch whether partners turn experiments into routine shopping.
Competes with Mastercard Agent Pay (Mastercard) · Universal Commerce Protocol/AP2 (Google ecosystem)
In plain English
Visa Intelligent Commerce is built for software assistants that search and shop for a person. It gives each assistant a protected payment credential — a stand-in for the real card details — plus rules that prove the buyer approved the purchase. Think of it as a permission slip that can also pay.
There is no disclosed revenue yet. The bet is that keeping these automated purchases trusted and inside Visa's network will eventually create payment volume and demand for security tools. Sellers, banks and software developers must all connect, and responsibility for a bad purchase still needs clear rules.
Value-Added Services
Fraud checks, bank software, seller payment tools and consulting form Visa's main growth layer. By June 2026, customers had committed $5.6B to future service work; watch whether these add-ons keep outgrowing the card network.
Competes with Marqeta Platform (Marqeta) · Stripe Payments (Stripe) · RiskOps (Feedzai) · Mastercard Advisors (Mastercard)
In plain English
The add-ons around a payment can be as valuable as moving the payment itself. Visa helps banks run card accounts, helps sellers take payments, catches suspicious activity and advises clients on how to improve their payment business.
Some customers pay each time a tool is used; others pay for ongoing software or a consulting job. Because some of these services can work on payments that do not travel through Visa's own card network, they open a larger pool of buyers. Banks and sellers keep paying when the tools reduce fraud, simplify operations or help them sell more.
Visa Stablecoin Platform
A July 2026 beta lets selected institutions create, destroy, move and manage digital coins designed to hold a steady value. Customers and pricing remain undisclosed; watch for paid users after the test phase.
Competes with Digital Asset Solutions (Mastercard) · Stablecoin Payments (Fireblocks)
In plain English
A stable-value digital coin is online money meant to stay close to a regular currency. Visa's new platform gives selected institutions software connections for creating those coins, removing them from circulation, moving them and managing the digital wallets that hold them.
It is still a beta test, so there are no named customers, prices or sales to judge, and Visa has not said how it will charge. The test is whether institutions become paying users. The business also depends on secure storage, reliable conversion back to ordinary money, enough buyers and sellers, and workable rules.
Visa Commercial Solutions
Cards, digital card numbers and spending controls help companies pay for travel and supplier bills. Payment volume grew 13% in fiscal Q3 FY2026; watch business travel and whether more large invoices shift from checks and manual transfers.
Competes with Mastercard Virtual Cards (Mastercard) · American Express Corporate Program (American Express)
In plain English
The company card has grown up. Visa Commercial Solutions covers plastic cards, digital card numbers and software that let employers set limits, pay suppliers and track travel or other spending. Banks provide the accounts and carry the risk if a company does not repay.
Visa earns network and tool fees when businesses spend or send payments. Banks keep offering it because controls and cleaner records make company spending easier to manage; suppliers matter because a payment only works where they agree to take it. Growth rises with business travel and the shift of large invoices away from checks and manual bank transfers.
Visa Direct
Pushes money to cards, bank accounts and digital wallets for people, companies and governments. Transfer count grew 21% in fiscal Q3 FY2026; watch its reach outside cards and the checks required before money can move.
Competes with Mastercard Move (Mastercard) · FedNow Service (Federal Reserve)
In plain English
Instead of waiting for a card purchase, Visa Direct starts with someone who wants to send money out: a business refunding a customer, a government paying a benefit or a person sending money abroad. It routes the payment to a card, bank account or digital wallet.
Banks, money-transfer companies and wallet providers connect their systems to the service and pay fees as transfers pass through. They keep using it when Visa can reach more recipients through one connection. Each route still depends on identity checks, enough local currency and the receiving network being available.


 Consumer PaymentsCredit, debit and prepaid card payments remain Visa's cash engine. One unnamed client supplied 11% of total FY2025 revenue; watch the rebates used to retain banks, regulation and spending that crosses borders.
Credit, debit and prepaid card payments remain Visa's cash engine. One unnamed client supplied 11% of total FY2025 revenue; watch the rebates used to retain banks, regulation and spending that crosses borders.
In plain English
Think of Visa as the switchboard behind a card purchase. Your bank approves the payment, the seller's bank receives it, and Visa's network passes the messages needed to check, record and finish the transaction. Visa itself is not the bank and usually does not take the risk that a shopper fails to repay.
Banks pay Visa fees tied to how much people spend, how many payments the network handles and whether money crosses borders or changes currency. More cards and more sellers make the network useful to both sides, so banks keep distributing Visa ways to pay.
Competes with Mastercard payment network (Mastercard) · American Express Global Network (American Express)
 Visa Intelligent CommercePayment controls let automated shopping assistants buy with a user's permission. By December 2025, only hundreds of controlled purchases had been completed; watch whether partners turn experiments into routine shopping.
Payment controls let automated shopping assistants buy with a user's permission. By December 2025, only hundreds of controlled purchases had been completed; watch whether partners turn experiments into routine shopping.
In plain English
Visa Intelligent Commerce is built for software assistants that search and shop for a person. It gives each assistant a protected payment credential — a stand-in for the real card details — plus rules that prove the buyer approved the purchase. Think of it as a permission slip that can also pay.
There is no disclosed revenue yet. The bet is that keeping these automated purchases trusted and inside Visa's network will eventually create payment volume and demand for security tools. Sellers, banks and software developers must all connect, and responsibility for a bad purchase still needs clear rules.
Competes with Mastercard Agent Pay (Mastercard) · Universal Commerce Protocol/AP2 (Google ecosystem)
 Value-Added ServicesFraud checks, bank software, seller payment tools and consulting form Visa's main growth layer. By June 2026, customers had committed $5.6B to future service work; watch whether these add-ons keep outgrowing the card network.
Fraud checks, bank software, seller payment tools and consulting form Visa's main growth layer. By June 2026, customers had committed $5.6B to future service work; watch whether these add-ons keep outgrowing the card network.
In plain English
The add-ons around a payment can be as valuable as moving the payment itself. Visa helps banks run card accounts, helps sellers take payments, catches suspicious activity and advises clients on how to improve their payment business.
Some customers pay each time a tool is used; others pay for ongoing software or a consulting job. Because some of these services can work on payments that do not travel through Visa's own card network, they open a larger pool of buyers. Banks and sellers keep paying when the tools reduce fraud, simplify operations or help them sell more.
Competes with Marqeta Platform (Marqeta) · Stripe Payments (Stripe) · RiskOps (Feedzai) · Mastercard Advisors (Mastercard)
 Visa Stablecoin PlatformA July 2026 beta lets selected institutions create, destroy, move and manage digital coins designed to hold a steady value. Customers and pricing remain undisclosed; watch for paid users after the test phase.
A July 2026 beta lets selected institutions create, destroy, move and manage digital coins designed to hold a steady value. Customers and pricing remain undisclosed; watch for paid users after the test phase.
In plain English
A stable-value digital coin is online money meant to stay close to a regular currency. Visa's new platform gives selected institutions software connections for creating those coins, removing them from circulation, moving them and managing the digital wallets that hold them.
It is still a beta test, so there are no named customers, prices or sales to judge, and Visa has not said how it will charge. The test is whether institutions become paying users. The business also depends on secure storage, reliable conversion back to ordinary money, enough buyers and sellers, and workable rules.
Competes with Digital Asset Solutions (Mastercard) · Stablecoin Payments (Fireblocks)
 Visa Commercial SolutionsCards, digital card numbers and spending controls help companies pay for travel and supplier bills. Payment volume grew 13% in fiscal Q3 FY2026; watch business travel and whether more large invoices shift from checks and manual transfers.
Cards, digital card numbers and spending controls help companies pay for travel and supplier bills. Payment volume grew 13% in fiscal Q3 FY2026; watch business travel and whether more large invoices shift from checks and manual transfers.
In plain English
The company card has grown up. Visa Commercial Solutions covers plastic cards, digital card numbers and software that let employers set limits, pay suppliers and track travel or other spending. Banks provide the accounts and carry the risk if a company does not repay.
Visa earns network and tool fees when businesses spend or send payments. Banks keep offering it because controls and cleaner records make company spending easier to manage; suppliers matter because a payment only works where they agree to take it. Growth rises with business travel and the shift of large invoices away from checks and manual bank transfers.
Competes with Mastercard Virtual Cards (Mastercard) · American Express Corporate Program (American Express)
 Visa DirectPushes money to cards, bank accounts and digital wallets for people, companies and governments. Transfer count grew 21% in fiscal Q3 FY2026; watch its reach outside cards and the checks required before money can move.
Pushes money to cards, bank accounts and digital wallets for people, companies and governments. Transfer count grew 21% in fiscal Q3 FY2026; watch its reach outside cards and the checks required before money can move.
In plain English
Instead of waiting for a card purchase, Visa Direct starts with someone who wants to send money out: a business refunding a customer, a government paying a benefit or a person sending money abroad. It routes the payment to a card, bank account or digital wallet.
Banks, money-transfer companies and wallet providers connect their systems to the service and pay fees as transfers pass through. They keep using it when Visa can reach more recipients through one connection. Each route still depends on identity checks, enough local currency and the receiving network being available.
Competes with Mastercard Move (Mastercard) · FedNow Service (Federal Reserve)
Named in filings, launches and programs
- Issuing SolutionsProduct lineAccount software, card setup, payment credentials, benefits and loyalty tools sold to banks and financial-technology companies.
- Acceptance SolutionsProduct lineCheckout, fraud and payment-management tools for sellers, including payments that do not run on Visa's own card network.
- Risk and Security SolutionsProduct lineChecks payments and identities for fraud, helps approve genuine buyers and supports disputes when something goes wrong.
- Advisory and Other ServicesServiceConsulting, data analysis, managed work and marketing programs sold to banks and sellers.
- Visa A2AServiceLets U.K. shoppers pay straight from a bank account, with added protections when a purchase goes wrong.
- Visa Protect for A2AServiceScores bank-to-bank payments for fraud before money leaves the sender's account.
- Visa Flex CredentialPlatform · RampingOne way to pay that lets a user choose among funding sources and payment modes.
- Visa PayService · RampingConnects participating digital wallets to sellers that already accept Visa.
- Visa AcceptService · RampingTurns a compatible phone and Visa debit card into a way for a seller to accept tap payments.
- Visa+EcosystemA directory that uses simple aliases to connect participating person-to-person payment apps.
- Visa B2B ConnectEcosystemA bank-to-bank network for business payments that cross national borders.
- TinkBrandEuropean service that connects bank accounts and lets approved apps use their financial data.
- PismoBrandSoftware for running bank accounts and processing cards, now expanding inside Visa's bank-services tools.
- Visa DPSPlatformRuns debit, prepaid and credit card programs for banks.
- CybersourcePlatformLarge-seller checkout, fraud and payment-management system inside Acceptance Solutions.
- Authorize.netPlatformPayment gateway for smaller sellers and the firms that resell payment services to them.
- FeaturespaceBrandFraud-detection technology acquired in December 2024 that adjusts its models as payment behavior changes.
- BioCatchPlatform · AnnouncedProposed $2.4B purchase would add fraud checks based on how a person behaves while using a device; Visa does not own it yet.
- Trusted Agent ProtocolEcosystemLets sellers tell approved automated shopping software from malicious bots.
Issuing SolutionsProduct line
Account software, card setup, payment credentials, benefits and loyalty tools sold to banks and financial-technology companies.
Acceptance SolutionsProduct line
Checkout, fraud and payment-management tools for sellers, including payments that do not run on Visa's own card network.
Risk and Security SolutionsProduct line
Checks payments and identities for fraud, helps approve genuine buyers and supports disputes when something goes wrong.
Advisory and Other ServicesService
Consulting, data analysis, managed work and marketing programs sold to banks and sellers.
Visa A2AService
Lets U.K. shoppers pay straight from a bank account, with added protections when a purchase goes wrong.
Visa Protect for A2AService
Scores bank-to-bank payments for fraud before money leaves the sender's account.
Visa Flex CredentialPlatform · Ramping
One way to pay that lets a user choose among funding sources and payment modes.
Visa PayService · Ramping
Connects participating digital wallets to sellers that already accept Visa.
Visa AcceptService · Ramping
Turns a compatible phone and Visa debit card into a way for a seller to accept tap payments.
Visa+Ecosystem
A directory that uses simple aliases to connect participating person-to-person payment apps.
Visa B2B ConnectEcosystem
A bank-to-bank network for business payments that cross national borders.
TinkBrand
European service that connects bank accounts and lets approved apps use their financial data.
PismoBrand
Software for running bank accounts and processing cards, now expanding inside Visa's bank-services tools.
Visa DPSPlatform
Runs debit, prepaid and credit card programs for banks.
CybersourcePlatform
Large-seller checkout, fraud and payment-management system inside Acceptance Solutions.
Authorize.netPlatform
Payment gateway for smaller sellers and the firms that resell payment services to them.
FeaturespaceBrand
Fraud-detection technology acquired in December 2024 that adjusts its models as payment behavior changes.
BioCatchPlatform · Announced
Proposed $2.4B purchase would add fraud checks based on how a person behaves while using a device; Visa does not own it yet.
Trusted Agent ProtocolEcosystem
Lets sellers tell approved automated shopping software from malicious bots.