
Wells Fargo (WFC)
Banking, lending, wealth management, and capital-markets services for U.S. consumers and businesses.
Something off on this page? Send us feedback.
Wells Fargo is a vast deposit-and-lending machine: households and businesses leave money with it, and it earns from putting that money to work. Most income comes from the gap between what loans and investments earn and what funding costs, while wealth advice, company finance and trading broaden the engine. After years under a regulatory growth restraint, the bank is expanding again, with its faster push in corporate markets, dealmaking and auto loans.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
9 in detail · 11 more below
Consumer, Small and Business Banking
Checking, savings and payments are the core business, producing $25.427 billion in fiscal 2025. Watch whether Wells can keep those deposits without paying so much for them that the lending profit shrinks.
Competes with Chase checking and deposits (JPMorgan Chase) · Chime Checking Account (Chime)
In plain English
This is where paychecks land, bills leave and small firms keep the cash needed for tomorrow. Wells serves households and small businesses through accounts, branches, its app and Fargo, the helper built into its digital banking.
Think of deposits as a reservoir. Wells pays customers for some of that water, then earns more by lending or investing it; the difference becomes income. Account and payment fees add another stream. Customers stay when moving their daily money elsewhere feels harder than the benefit of switching.
Credit Card
Consumer and small-business cards brought in $6.375 billion in fiscal 2025. New accounts are growing quickly, but rewards, fraud and unpaid balances can consume much of what each swipe and loan earns.
Competes with Chase credit cards (JPMorgan Chase) · Capital One credit cards (Capital One)
In plain English
A card lets someone buy now and settle with Wells later. If the bill is carried forward, Wells charges interest; each purchase also brings a fee funded through the merchant payment system.
The loop repeats whenever the card earns a place at the top of a wallet. Rewards help win that spot, but they are a real cost, as are fraud and customers who never repay. Wells therefore makes money from both spending and borrowing, provided its offers attract useful customers rather than expensive losses.
Home Lending
Mortgages produced $3.364 billion in fiscal 2025. Wells increasingly focuses on people who already use the bank, while high rates, scarce homes and affordability govern how often customers borrow or refinance.
Competes with Rocket Mortgage home loans (Rocket Companies) · Chase Home Lending/MyHome (JPMorgan Chase)
In plain English
Buying a home usually means borrowing most of the price and paying it back over many years. Wells finds borrowers through branches, advisers and digital channels, with a growing preference for customers who already have another relationship with the bank.
The bank earns interest while it keeps a mortgage, plus fees for arranging and looking after loans. It can also sell some loans to government-backed home-loan buyers. This business wakes up when people move or lower rates make a new loan worthwhile; when homes are unaffordable, the flow slows.
Auto
This is still a small line, but new auto financing rose 41% year over year in the second quarter of 2026. Growth depends on dealer access, vehicle sales and avoiding costly borrower defaults.
Competes with Capital One Auto Finance (Capital One) · Ally Auto Financing (Ally Financial)
In plain English
At the dealership, Wells can supply the money that turns a shopper into a buyer. Dealers and manufacturers send over applications; Wells approves selected borrowers, pays for the car and collects monthly payments with interest.
That dealer doorway matters because the loan is won where the purchase happens. Preferred financing through Volkswagen and Audi dealers helps bring in more borrowers. The trade is simple but unforgiving: rapid loan growth only pays if used-car values hold up and enough customers keep making their payments.
Markets
Trading, financing and price protection for large institutions generated $7.061 billion in fiscal 2025. Activity has accelerated, though this income still rises and falls with market swings and clients' appetite to trade.
Competes with FICC and Equities (Goldman Sachs) · Markets (JPMorgan Chase)
In plain English
Behind big companies and investment funds sits a market for bonds, which are promises to repay borrowed money, along with shares and currencies. Wells helps clients buy and sell, lends against their holdings and builds contracts that lock in a price or interest rate.
Picture a switchyard that routes risk instead of freight. The bank collects fees and trading gains for finding the other side, moving quickly and sometimes holding the risk itself. Busy, jumpy markets can bring more traffic, but they also demand funding, reliable trading partners and enough of Wells's own money to absorb mistakes.
Banking
Company loans, payment handling and help raising money produced $7.037 billion in fiscal 2025. The line grows when businesses borrow, sell bonds or shares, or pursue acquisitions; those windows can close abruptly.
Competes with J.P. Morgan Investment Banking (JPMorgan Chase) · Investment Banking (Morgan Stanley)
In plain English
When a company wants to buy a rival, build a plant or raise money from investors, Wells can help assemble the deal. It may lend directly, find investors for new bonds or shares, advise on a sale, and move the customer's day-to-day cash.
Payment fees and loan interest can repeat, while a major deal brings a larger one-time fee. Relationships are the thread: commercial bankers introduce clients, then specialist teams compete for the next assignment. Revenue follows business confidence, healthy borrowers and open markets for new financing.
Commercial Real Estate
Loans and related services for offices and other income-producing property made $5.083 billion in fiscal 2025. Weak offices, falling property values and difficult refinancing remain the fault lines to watch.
Competes with Capital Markets (Walker & Dunlop) · Mortgages and Structured Products (Goldman Sachs)
In plain English
A building can become the security behind a very large loan. Wells finances owners, developers and investors, then may keep the loan, sell pieces to investors or continue collecting payments for whoever owns it.
Interest and fees arrive as properties are bought, built or refinanced with a new loan. The crucial test comes from the building itself: rent must cover the debt, and its value must protect Wells if the borrower fails. Empty offices and expensive refinancing make this line more fragile than the revenue number alone suggests.
Wealth and Investment Management
Advice, brokerage, banking and trust services generated $16.328 billion in fiscal 2025. The business is growing faster than everyday banking, but its fees still depend heavily on market levels and keeping productive advisers.
Competes with Wealth Management (Morgan Stanley) · Merrill Wealth Management (Bank of America)
In plain English
People and institutions with complex finances pay Wells to help invest, protect and transfer their money. Advisers choose investments, execute trades and connect clients with loans, bank accounts and trust services, which handle assets for someone else's benefit.
Much of the fee rises as a client's investments grow and falls when markets shrink, like a gardener paid partly by the size of the orchard. Trading commissions and interest from loans add income. Clients keep paying for judgment and continuity, so adviser relationships and a dependable service platform are central.
Commercial Banking
Loans, deposits and payment services for middle-sized companies produced $11.978 billion in fiscal 2025. Its health follows business spending and borrower quality, while customer deposits also help fund the rest of Wells Fargo.
Competes with J.P. Morgan Commercial Banking (JPMorgan Chase) · Business Banking (Bank of America)
In plain English
For a middle-sized company, this is the bank behind payroll, supplier payments and the credit needed to buy inventory or equipment. Relationship managers join those daily services together and can introduce bigger financing teams when the customer outgrows an ordinary loan.
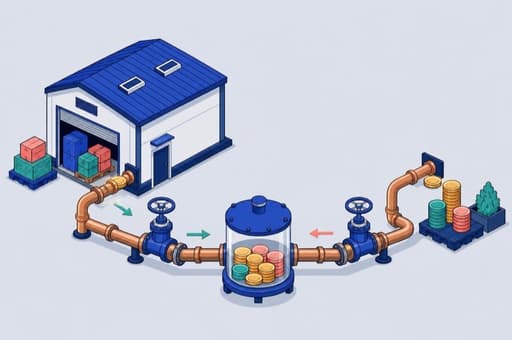
Think of it as the financial plumbing inside a business. Wells earns interest on loans, pays less on many deposits than it earns elsewhere, and charges fees to move and organize cash. The service sticks because replacing all those pipes is disruptive, but losses rise when customers struggle.


 Consumer, Small and Business BankingChecking, savings and payments are the core business, producing $25.427 billion in fiscal 2025. Watch whether Wells can keep those deposits without paying so much for them that the lending profit shrinks.
Checking, savings and payments are the core business, producing $25.427 billion in fiscal 2025. Watch whether Wells can keep those deposits without paying so much for them that the lending profit shrinks.
In plain English
This is where paychecks land, bills leave and small firms keep the cash needed for tomorrow. Wells serves households and small businesses through accounts, branches, its app and Fargo, the helper built into its digital banking.
Think of deposits as a reservoir. Wells pays customers for some of that water, then earns more by lending or investing it; the difference becomes income. Account and payment fees add another stream. Customers stay when moving their daily money elsewhere feels harder than the benefit of switching.
Competes with Chase checking and deposits (JPMorgan Chase) · Chime Checking Account (Chime)
 Credit CardConsumer and small-business cards brought in $6.375 billion in fiscal 2025. New accounts are growing quickly, but rewards, fraud and unpaid balances can consume much of what each swipe and loan earns.
Consumer and small-business cards brought in $6.375 billion in fiscal 2025. New accounts are growing quickly, but rewards, fraud and unpaid balances can consume much of what each swipe and loan earns.
In plain English
A card lets someone buy now and settle with Wells later. If the bill is carried forward, Wells charges interest; each purchase also brings a fee funded through the merchant payment system.
The loop repeats whenever the card earns a place at the top of a wallet. Rewards help win that spot, but they are a real cost, as are fraud and customers who never repay. Wells therefore makes money from both spending and borrowing, provided its offers attract useful customers rather than expensive losses.
Competes with Chase credit cards (JPMorgan Chase) · Capital One credit cards (Capital One)
 Home LendingMortgages produced $3.364 billion in fiscal 2025. Wells increasingly focuses on people who already use the bank, while high rates, scarce homes and affordability govern how often customers borrow or refinance.
Mortgages produced $3.364 billion in fiscal 2025. Wells increasingly focuses on people who already use the bank, while high rates, scarce homes and affordability govern how often customers borrow or refinance.
In plain English
Buying a home usually means borrowing most of the price and paying it back over many years. Wells finds borrowers through branches, advisers and digital channels, with a growing preference for customers who already have another relationship with the bank.
The bank earns interest while it keeps a mortgage, plus fees for arranging and looking after loans. It can also sell some loans to government-backed home-loan buyers. This business wakes up when people move or lower rates make a new loan worthwhile; when homes are unaffordable, the flow slows.
Competes with Rocket Mortgage home loans (Rocket Companies) · Chase Home Lending/MyHome (JPMorgan Chase)
 AutoThis is still a small line, but new auto financing rose 41% year over year in the second quarter of 2026. Growth depends on dealer access, vehicle sales and avoiding costly borrower defaults.
This is still a small line, but new auto financing rose 41% year over year in the second quarter of 2026. Growth depends on dealer access, vehicle sales and avoiding costly borrower defaults.
In plain English
At the dealership, Wells can supply the money that turns a shopper into a buyer. Dealers and manufacturers send over applications; Wells approves selected borrowers, pays for the car and collects monthly payments with interest.
That dealer doorway matters because the loan is won where the purchase happens. Preferred financing through Volkswagen and Audi dealers helps bring in more borrowers. The trade is simple but unforgiving: rapid loan growth only pays if used-car values hold up and enough customers keep making their payments.
Competes with Capital One Auto Finance (Capital One) · Ally Auto Financing (Ally Financial)
 MarketsTrading, financing and price protection for large institutions generated $7.061 billion in fiscal 2025. Activity has accelerated, though this income still rises and falls with market swings and clients' appetite to trade.
Trading, financing and price protection for large institutions generated $7.061 billion in fiscal 2025. Activity has accelerated, though this income still rises and falls with market swings and clients' appetite to trade.
In plain English
Behind big companies and investment funds sits a market for bonds, which are promises to repay borrowed money, along with shares and currencies. Wells helps clients buy and sell, lends against their holdings and builds contracts that lock in a price or interest rate.
Picture a switchyard that routes risk instead of freight. The bank collects fees and trading gains for finding the other side, moving quickly and sometimes holding the risk itself. Busy, jumpy markets can bring more traffic, but they also demand funding, reliable trading partners and enough of Wells's own money to absorb mistakes.
Competes with FICC and Equities (Goldman Sachs) · Markets (JPMorgan Chase)
 BankingCompany loans, payment handling and help raising money produced $7.037 billion in fiscal 2025. The line grows when businesses borrow, sell bonds or shares, or pursue acquisitions; those windows can close abruptly.
Company loans, payment handling and help raising money produced $7.037 billion in fiscal 2025. The line grows when businesses borrow, sell bonds or shares, or pursue acquisitions; those windows can close abruptly.
In plain English
When a company wants to buy a rival, build a plant or raise money from investors, Wells can help assemble the deal. It may lend directly, find investors for new bonds or shares, advise on a sale, and move the customer's day-to-day cash.
Payment fees and loan interest can repeat, while a major deal brings a larger one-time fee. Relationships are the thread: commercial bankers introduce clients, then specialist teams compete for the next assignment. Revenue follows business confidence, healthy borrowers and open markets for new financing.
Competes with J.P. Morgan Investment Banking (JPMorgan Chase) · Investment Banking (Morgan Stanley)
 Commercial Real EstateLoans and related services for offices and other income-producing property made $5.083 billion in fiscal 2025. Weak offices, falling property values and difficult refinancing remain the fault lines to watch.
Loans and related services for offices and other income-producing property made $5.083 billion in fiscal 2025. Weak offices, falling property values and difficult refinancing remain the fault lines to watch.
In plain English
A building can become the security behind a very large loan. Wells finances owners, developers and investors, then may keep the loan, sell pieces to investors or continue collecting payments for whoever owns it.
Interest and fees arrive as properties are bought, built or refinanced with a new loan. The crucial test comes from the building itself: rent must cover the debt, and its value must protect Wells if the borrower fails. Empty offices and expensive refinancing make this line more fragile than the revenue number alone suggests.
Competes with Capital Markets (Walker & Dunlop) · Mortgages and Structured Products (Goldman Sachs)
 Wealth and Investment ManagementAdvice, brokerage, banking and trust services generated $16.328 billion in fiscal 2025. The business is growing faster than everyday banking, but its fees still depend heavily on market levels and keeping productive advisers.
Advice, brokerage, banking and trust services generated $16.328 billion in fiscal 2025. The business is growing faster than everyday banking, but its fees still depend heavily on market levels and keeping productive advisers.
In plain English
People and institutions with complex finances pay Wells to help invest, protect and transfer their money. Advisers choose investments, execute trades and connect clients with loans, bank accounts and trust services, which handle assets for someone else's benefit.
Much of the fee rises as a client's investments grow and falls when markets shrink, like a gardener paid partly by the size of the orchard. Trading commissions and interest from loans add income. Clients keep paying for judgment and continuity, so adviser relationships and a dependable service platform are central.
Competes with Wealth Management (Morgan Stanley) · Merrill Wealth Management (Bank of America)
 Commercial BankingLoans, deposits and payment services for middle-sized companies produced $11.978 billion in fiscal 2025. Its health follows business spending and borrower quality, while customer deposits also help fund the rest of Wells Fargo.
Loans, deposits and payment services for middle-sized companies produced $11.978 billion in fiscal 2025. Its health follows business spending and borrower quality, while customer deposits also help fund the rest of Wells Fargo.
In plain English
For a middle-sized company, this is the bank behind payroll, supplier payments and the credit needed to buy inventory or equipment. Relationship managers join those daily services together and can introduce bigger financing teams when the customer outgrows an ordinary loan.
Think of it as the financial plumbing inside a business. Wells earns interest on loans, pays less on many deposits than it earns elsewhere, and charges fees to move and organize cash. The service sticks because replacing all those pipes is disruptive, but losses rise when customers struggle.
Competes with J.P. Morgan Commercial Banking (JPMorgan Chase) · Business Banking (Bank of America)
Named in filings, launches and programs
- Personal LendingProduct lineUnsecured personal loans added about $1.18 billion of fiscal 2025 revenue inside the consumer bank.
- CorporateSegmentCentral treasury, venture investments and other company-level activities added $747 million of fiscal 2025 revenue.
- Wells Fargo PremierService · RampingA coordinated mix of banking and advice for affluent customers, and an area receiving investment in fiscal 2026.
- Wells Fargo AdvisorsServiceThe employee and independent-adviser network that carries Wells Fargo's wealth services to clients.
- FargoPlatformThe built-in helper for consumer digital banking, with more capabilities planned.
- VantagePlatformDigital banking for commercial and corporate clients, with added payment and account-service tools planned.
- Advisor GatewayPlatform · RampingA single work screen for advisers whose rollout was set to begin in the second quarter of 2026.
- Overland AdvantageCustomer program · RampingA direct-lending partnership with Centerbridge that had arranged about $7 billion of completed financing by January 2026.
- Volkswagen and Audi Preferred Purchase-Financing ProgramCustomer programDealer-routed auto financing begun in 2025 that helped feed later loan-balance growth.
- Expedia One Key CardsCustomer programTwo cards launched jointly with Expedia Group and Mastercard under a multi-year agreement.
- Tokenized DepositsProduct · Pre-revenueA planned test for exchanging digital dollar and pound deposits in fall 2026, ahead of a broader 2027 rollout.
Personal LendingProduct line
Unsecured personal loans added about $1.18 billion of fiscal 2025 revenue inside the consumer bank.
CorporateSegment
Central treasury, venture investments and other company-level activities added $747 million of fiscal 2025 revenue.
Wells Fargo PremierService · Ramping
A coordinated mix of banking and advice for affluent customers, and an area receiving investment in fiscal 2026.
Wells Fargo AdvisorsService
The employee and independent-adviser network that carries Wells Fargo's wealth services to clients.
FargoPlatform
The built-in helper for consumer digital banking, with more capabilities planned.
VantagePlatform
Digital banking for commercial and corporate clients, with added payment and account-service tools planned.
Advisor GatewayPlatform · Ramping
A single work screen for advisers whose rollout was set to begin in the second quarter of 2026.
Overland AdvantageCustomer program · Ramping
A direct-lending partnership with Centerbridge that had arranged about $7 billion of completed financing by January 2026.
Volkswagen and Audi Preferred Purchase-Financing ProgramCustomer program
Dealer-routed auto financing begun in 2025 that helped feed later loan-balance growth.
Expedia One Key CardsCustomer program
Two cards launched jointly with Expedia Group and Mastercard under a multi-year agreement.
Tokenized DepositsProduct · Pre-revenue
A planned test for exchanging digital dollar and pound deposits in fall 2026, ahead of a broader 2027 rollout.